A battery's value depends on more than its energy capacity. It must also deliver consistent performance, meet safety requirements, comply with applicable standards, and remain reliable throughout its intended use. As batteries become increasingly important to electric vehicles, consumer electronics, and renewable energy storage, testing, inspection, and certification services are becoming an essential part of the battery industry's development.
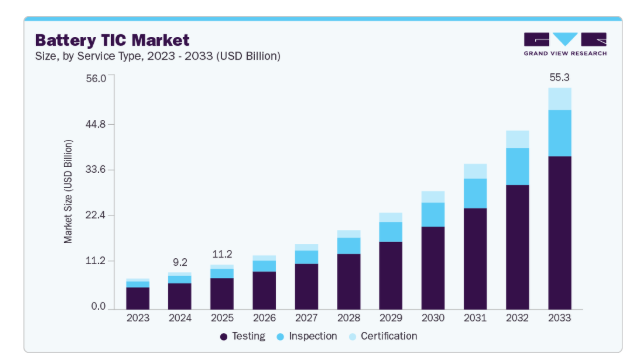
The Battery Testing, Inspection, and Certification Market was valued at USD 9.2 billion in 2024 and is projected to grow from USD 13.5 billion in 2026 to USD 55.3 billion by 2033, registering a CAGR of 22.2% from 2025 to 2033. This expansion reflects the growing need to validate battery safety and performance as battery technologies and applications continue to evolve.
The Battery Industry Cannot Scale Without Testing
The rapid adoption of electric vehicles and energy storage systems is increasing the demand for batteries that satisfy performance and safety requirements. Lithium-ion batteries are widely used in these applications because of their high energy density and extended lifespan. However, their growing deployment also increases the importance of comprehensive testing and certification.
Battery TIC services help manufacturers evaluate whether products meet technical specifications and relevant regulatory requirements. These services can identify performance limitations, support product validation, and help reduce the risks associated with battery failures. As governments and regulatory bodies introduce stricter standards, testing and certification become increasingly important for manufacturers seeking to bring products to market.
Technological development is adding another layer of demand. Emerging battery technologies, including solid-state and lithium-sulfur batteries, require specialized evaluation to validate their performance and safety characteristics. As a result, TIC providers must develop the capabilities needed to assess both established battery chemistries and newer technologies.
Five Market Segments Reveal Where Demand Is Concentrated
The market's growth is not uniform across services, standards, battery chemistries, and applications. Its segment structure highlights where testing activity is currently concentrated and where faster expansion is expected.
Download a free sample report or claim your copy of this full market intelligence report
Testing services remain the foundation. Testing accounted for 71.3% of market revenue in 2024, making it the leading service category. Demand is supported by the need to assess battery performance, safety, and reliability across electric vehicles and energy storage systems. Certification, however, is expected to grow at the fastest CAGR over the forecast period as manufacturers seek documented evidence that products satisfy evolving technical and regulatory requirements.
Safety testing leads, while performance testing gains momentum. Safety testing held the largest revenue share in 2024 because battery failures can create serious operational risks. Increasing battery complexity and regulatory scrutiny reinforce the need for comprehensive safety assessments. Performance testing is expected to record the fastest growth as manufacturers seek to improve efficiency, energy density, and battery longevity.
In-house testing leads, but outsourcing is expanding. In-house services accounted for the largest share in 2024. Internal facilities give manufacturers greater control over testing schedules, confidentiality, and product-specific procedures. Nevertheless, outsourced TIC services are expected to grow at the fastest rate. External providers offer specialized expertise, advanced testing capabilities, flexibility, and access to services without requiring manufacturers to make equivalent investments in their own infrastructure.
Lithium-ion dominates battery chemistry demand. Lithium-ion batteries held the largest market share in 2024, reflecting their widespread use in electric vehicles, consumer electronics, and energy storage systems. Lead-acid batteries are expected to grow at the fastest CAGR among battery types during the forecast period, supported by their cost-effectiveness, reliability, recycling capabilities, and use in backup power, automotive, and renewable energy storage applications.
Electric vehicles lead applications, while consumer electronics grows rapidly. Electric vehicles represented 37.6% of market revenue in 2024. Rising EV adoption and the need to verify battery safety and reliability support this position. Consumer electronics is projected to register the fastest application-segment CAGR at 24.1% from 2025 to 2033, driven by demand for batteries with greater energy density, longer life cycles, and dependable performance in smartphones, laptops, tablets, and wearable devices.
Regional Market Dynamics: Manufacturing, Regulation, and Testing Capacity
Asia Pacific accounted for 34.6% of global revenue in 2024 and is anticipated to register the highest CAGR through 2033. China, Japan, and South Korea are major battery manufacturing and innovation centers, supporting demand for TIC services across electric vehicles, consumer electronics, and energy storage. China also led the regional market in 2024.
North America represents another important market, with battery technology investment, manufacturing expansion, and clean-energy policies supporting demand for testing capabilities. In April 2025, SGS expanded its laboratory in Suwanee, Georgia, to strengthen testing services for light electric vehicles and energy storage systems. The facility supports testing up to 100V and 1,200A, increasing regional capacity for these applications.
Europe's market outlook is supported by climate objectives, stringent regulatory requirements, and investments in battery manufacturing and research. Germany, France, and Sweden are among the countries contributing to the region's battery technology development and testing ecosystem.
Across regions, local testing capacity is becoming strategically important. Facilities that can evaluate products closer to manufacturing and deployment locations may help companies manage certification timelines and address market-specific requirements more efficiently.
What Will Determine the Market's Next Phase?
The projected rise to USD 55.3 billion by 2033 highlights the growing importance of independent testing and certification within the battery value chain. Continued EV adoption, expansion of energy storage systems, advances in battery chemistry, and rising consumer electronics demand are expected to support further market development.
At the same time, manufacturers face a more complex validation environment as technologies evolve and regulatory expectations become more demanding. Providers that can deliver specialized testing, reliable certification, and flexible service models will be positioned to address these requirements.
The Battery Testing, Inspection, and Certification Market is therefore becoming more than a supporting service industry. It is an important part of enabling battery technologies to achieve the safety, performance, and reliability required for wider adoption.
Explore Our Research & Intelligence Solutions
Prism AI: Ask. Analyze. Get Cited Market Insights. – Explore Now
Grand View Signal: Understand the Factors Shaping Commodity Prices – Explore the Platform