Closing a business involves more than ending daily operations. Owners must settle outstanding obligations, organize records, manage inventory, and determine what to do with equipment and other company assets. A structured asset-disposal plan can help simplify the process and ensure that valuable items are handled responsibly.
Create a Complete Asset Inventory
The first step is to identify the assets owned by the business. These may include industrial machinery, commercial vehicles, office furniture, tools, computers, and other equipment.
Owners should record each item's condition, approximate value, ownership status, and location. Reviewing this information helps distinguish assets that can be sold from items that need to be returned, transferred, or disposed of through another appropriate process.
Prepare Assets for Potential Buyers
Accurate descriptions make it easier for prospective buyers to assess available assets. Businesses should collect model numbers, specifications, maintenance records, photographs, and other relevant documentation.
Equipment should be presented honestly, with known defects and limitations disclosed. Where appropriate, arranging inspections can help potential buyers make informed decisions before committing to a purchase.
Compare Asset-Selling Options
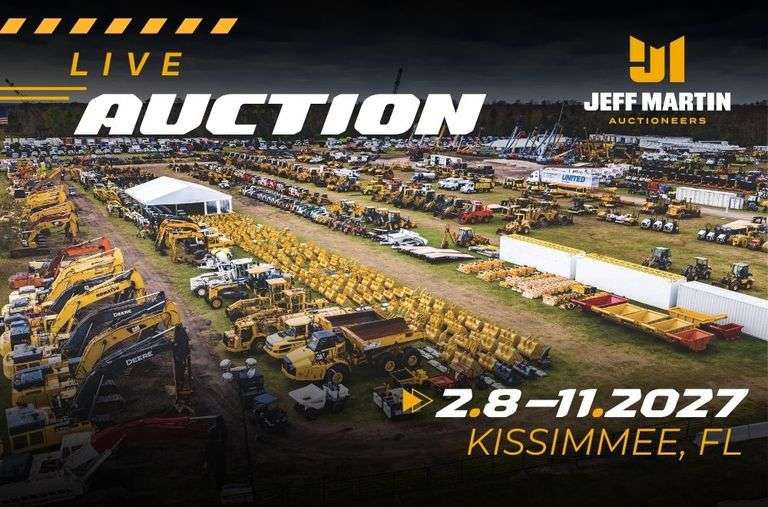
Different selling methods may suit different types and quantities of assets. Individual sales can work for selected items, while selling multiple assets through an organized auction may help streamline the process.
Businesses exploring Business Liquidation Auctions can compare auction terms, seller fees, bidding procedures, payment arrangements, and collection requirements before deciding how to proceed.
Understand Financial and Legal Obligations
Before selling company assets, owners should confirm that they have the authority to sell them. Equipment subject to financing, leasing agreements, security interests, or other restrictions may require additional steps.
Businesses should also maintain accurate records of sales proceeds and related expenses. Depending on the circumstances and jurisdiction, tax obligations, creditor rights, and formal insolvency or dissolution procedures may apply. Professional legal and accounting advice can help clarify these responsibilities.
Plan Logistics and Asset Collection
Large machinery and commercial equipment may require specialist lifting, dismantling, or transportation. Sellers should establish clear collection deadlines and confirm access arrangements with buyers.
If a facility is being vacated, asset removal should be coordinated with the building handover and any remaining operational activities. Advance planning can help prevent delays and unexpected expenses.
Keep Documentation Organized
A clear record of each transaction supports accountability throughout the closure process. Businesses should retain relevant invoices, sale agreements, payment confirmations, equipment descriptions, and collection records.
Organized documentation can also help accountants and legal advisers reconcile assets and complete outstanding administrative requirements.